
How Many Credit Scores Do You Have? (And Why Your Mortgage Uses Just 3)
How many credit scores do you have? Realistically a dozen-plus across FICO versions and VantageScore. Here is why your mortgage deliberately uses the same trusted three.

How many credit scores do you have? Realistically a dozen-plus across FICO versions and VantageScore. Here is why your mortgage deliberately uses the same trusted three.

What credit score do you need to buy a house? The honest answer: "allowed" isn't "approvable." See real floors by loan program (VA, USDA, FHA, conventional) from a Colorado Springs broker.
APR rolls your up-front lender fees into one rate so you can compare loans, but it's also the one number lenders can game by choosing which fees to include. Here's how to read the spread and when the lowest APR loses.
Rate shopping by the number on the rate sheet is how borrowers overpay. The right way to compare two or three offers is by true cost over the exact years you'll keep the loan, including the break-even month where a pricier-up-front loan finally pulls ahead.
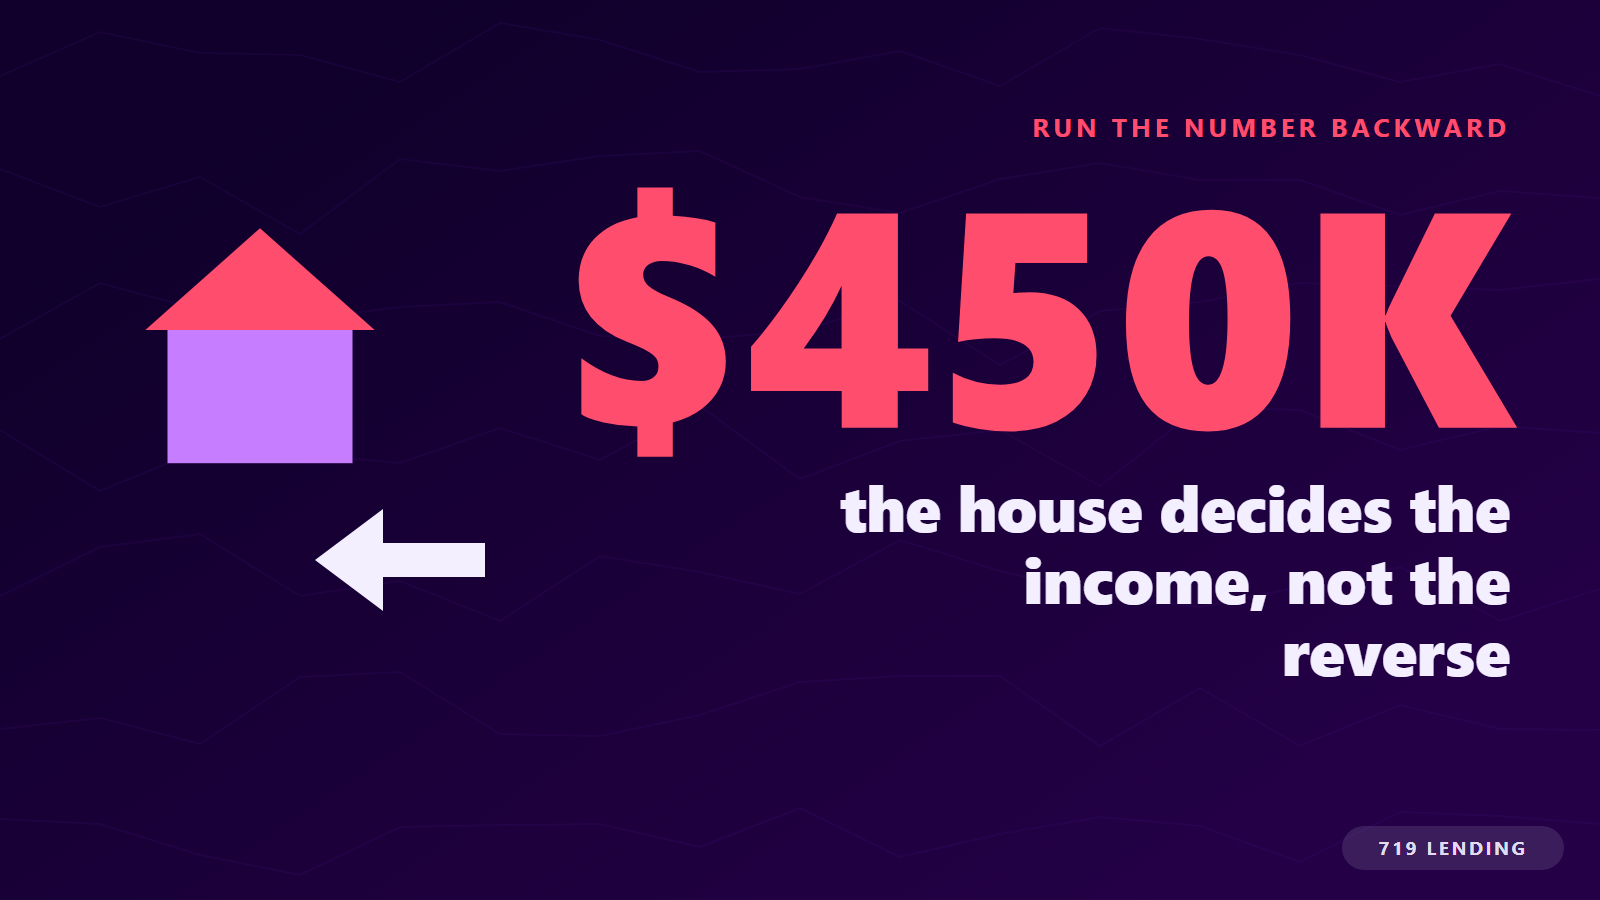
Every mortgage calculator asks what you earn and spits out a home price. This one flips it: tell it the house you want, and it tells you the paycheck a lender needs to see, monthly and annual, before taxes, plus the four levers that lower it.
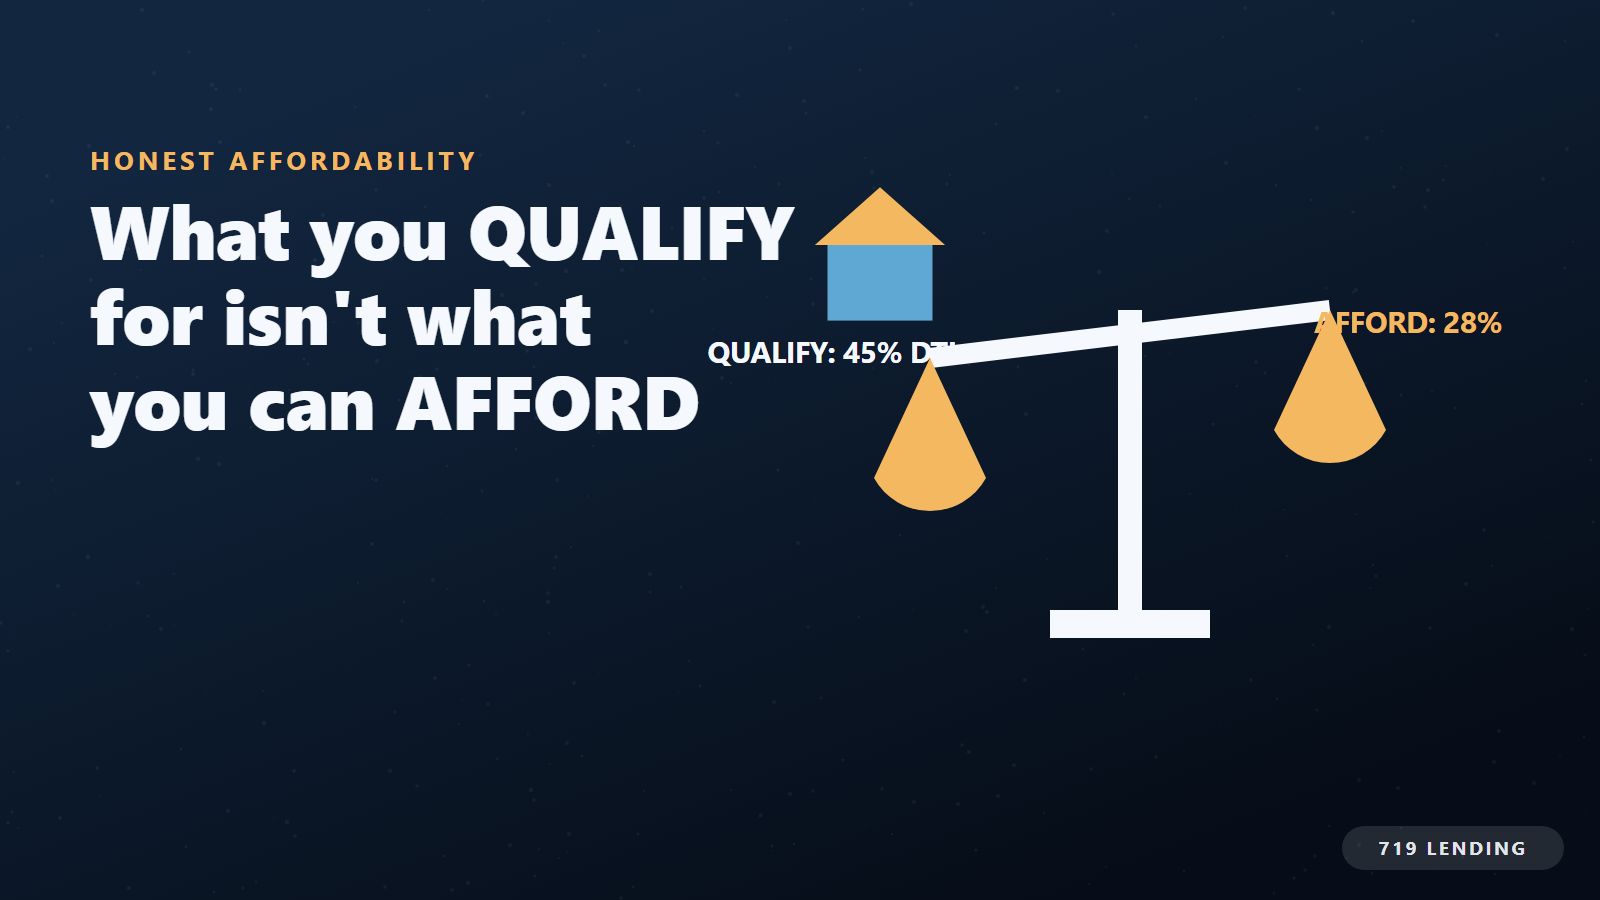
Most affordability calculators quietly ignore taxes, insurance, and PMI — which is exactly why their "max price" runs too high. Here's how 719's What Can I Afford tool solves the chicken-and-egg problem of escrow costs that grow with the price you're trying to find.

The Residual Income Effect: why the real dollars left after your mortgage can matter more than your DTI ratio, and why the VA loan is the only major program that requires it. A 719 Lending view.
CHFA Schools To Home launches July 2026, offering Colorado public school employees up to 25% of the first mortgage in down payment assistance. Here's how it works.
Rent vs. own in Colorado Springs, framed as long-term wealth-building. Forced savings, the FHFA home-price trend, and the Fed's homeowner-renter wealth gap — with an honest look at the risks.
A great credit score alone doesn't approve a mortgage. Learn the Four C's underwriters actually weigh — Credit, Capacity, Capital, Collateral — and how a Colorado Springs broker reads the whole file.