Federal law gives borrowers a right of rescission on most non-purchase money mortgages, meaning refinances and home equity loans. Here is exactly how the three-business-day window works, when the clock starts, how to deliver written notice, and what happens after you cancel.
Rescind a Refinance: Do You Still Owe the Original Loan?
If you rescind a refinance loan, do you still owe the original loan? Yes, you do. Canceling the refinance unwinds the new loan, but your existing mortgage stays exactly where it was, and payments on it are still due.
This article explains how the right of rescission works for refinances and other non-purchase money mortgages, how the three-day clock runs, how to cancel correctly, and what happens to your original loan afterward. It is written for Colorado homeowners, including the many military families around Colorado Springs weighing a refinance decision.
- The right of rescission applies to most non-purchase money mortgages, such as refinances and home equity loans.
- You get three business days to cancel, and Saturdays count as business days while Sundays and legal public holidays do not.
- You must cancel in writing; a phone call or a visit to the lender is not enough.
- Within 20 calendar days after the lender receives your notice, money or property you paid as part of the transaction must be returned to you.
- Rescinding the refinance does not touch your original loan. You still owe it and must keep paying it.
The short answer: yes, the original loan comes back into play

Rescission cancels the refinance contract, not your debt. The Consumer Financial Protection Bureau (CFPB) is direct about this: your right to rescind does not change your obligation to make payments on any of your other loans.
In the CFPB’s words, if you refinance and then rescind the refinance loan, you will still have to pay the original loan. The refinance never replaced it, so nothing about your existing mortgage changed.
Practically, that means the payment schedule, servicer, and terms of your original mortgage continue as before. Keep making those payments on time, because a missed payment during the confusion can damage your credit report.
To understand why the original loan survives, it helps to know who the right of rescission actually covers.
Who does the right of rescission apply to?
The right of rescission applies to most non-purchase money mortgages. A non-purchase money mortgage is a mortgage that is not used to buy the home.
Refinances and home equity loans are the CFPB’s own examples of non-purchase money mortgages. If you refinanced the home you already own, this right is generally yours.
Non-purchase money mortgages explained
A non-purchase money mortgage attaches new financing to a home you already live in. Because you are pledging your existing residence, federal law builds in a cooling-off period so you can back out after signing.
You can cancel during the window for any reason or no reason at all. You do not have to justify the decision to the lender.
Loans that do not come with this window
A mortgage used to buy the home is, by definition, a purchase money mortgage, and the rescission right the CFPB describes covers non-purchase money loans. If you are unsure which category your transaction falls into, ask your loan officer or an attorney before you rely on the window.
Once you know the right applies, the next question is when the clock actually starts.
How does the three-day rescission clock work?
The right of rescission gives you three business days to cancel a non-purchase money mortgage agreement. But the clock does not necessarily start the moment you sign.
The three events that must all happen first
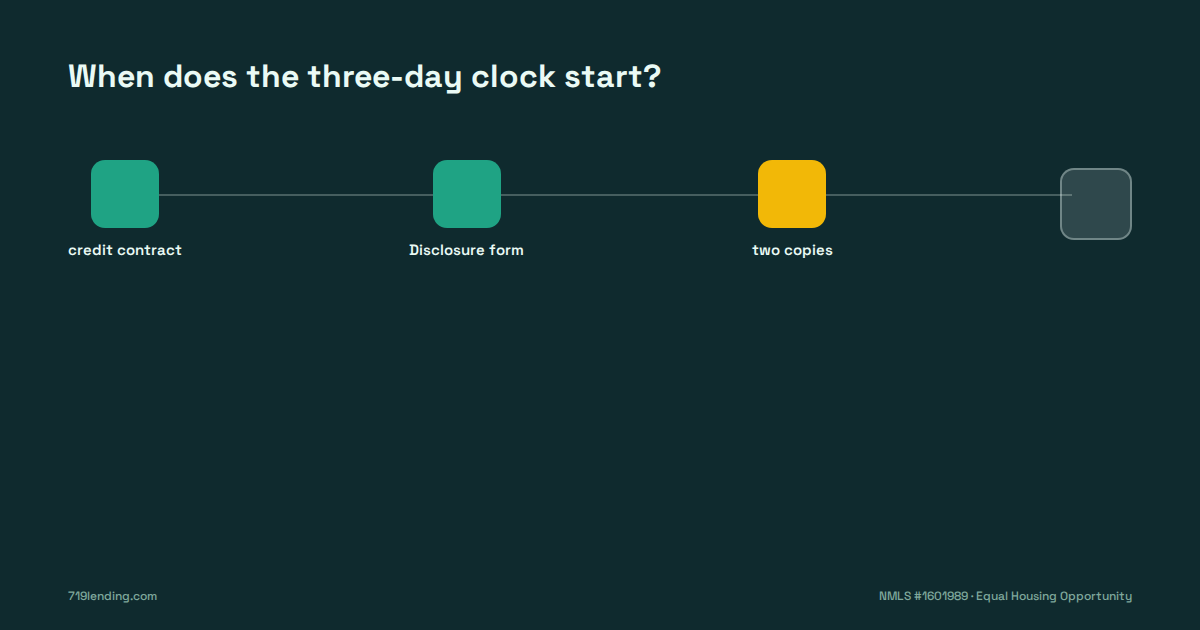
The three-day clock does not start until all three of these events have occurred. First, you sign the credit contract, usually known as the Promissory Note.
Second, you receive the appropriate and accurate Truth in Lending disclosure. For most loans applied for on or after October 3, 2015, that disclosure is the Closing Disclosure form.
Third, you receive two copies of a notice explaining your right to rescind. If any of the three is missing, the clock has not started.
Which days count as business days
For rescission purposes, business days include Saturdays but not Sundays or legal public holidays. So a refinance signed on a Thursday runs on a different calendar than one signed on a Friday.
Count carefully and confirm the exact deadline with your lender in writing. With the timing clear, the next piece is how to deliver a cancellation that actually counts.
How do you rescind a refinance the right way?
You must notify the lender in writing that you are canceling the loan contract and exercising your right to rescind. That is the only method that works.
Written notice only
You may use the form the lender provided or write a letter. You cannot rescind just by calling or visiting the lender, no matter how clearly you say it in person.
Keep a copy of whatever written notice you send. If a dispute ever arises about whether you canceled in time, that copy is your evidence.
The midnight deadline
Whatever form of written notice you use, make sure it is delivered or mailed before midnight of the third business day after closing. The CFPB’s tip is specific on this point: mailed or delivered by that midnight, with a copy kept for yourself.
Once the notice is in, the process shifts to what the lender owes you and what you still owe on the old loan.
What happens after you rescind?
Rescission triggers a specific unwinding process on the lender’s side, while your side of the ledger stays surprisingly simple.
The lender returns what you paid
Within 20 calendar days after the lender receives your notice of rescission, all money or property you paid as part of the mortgage transaction must be returned to you. That obligation runs on calendar days, not business days.
Track the date the lender received your notice so you know when the 20-day period ends.
The original loan stays in place
Meanwhile, your original mortgage continues as if the refinance never happened. It was never paid off, so the balance, the payment due dates, and the terms all remain in force.
Do not wait for the rescission dust to settle before making the next payment on the original loan. Rescission does not pause, defer, or forgive anything on your existing mortgage.
Here is the whole timeline in one place:
| Stage | Time frame | What happens |
|---|---|---|
| Rescission window opens | After all three triggering events | You sign the Promissory Note, receive the accurate Truth in Lending disclosure, and receive two copies of the rescission notice |
| Rescission window | Three business days | You may cancel in writing for any reason; Saturdays count, Sundays and legal public holidays do not |
| Lender refund | Within 20 calendar days of receiving your notice | Money or property you paid as part of the transaction must be returned to you |
| Extended rescission | Up to three years in limited cases | May apply if required disclosures were missing or contained certain important mistakes; consult a lawyer |
| Original loan | Ongoing, unchanged | You still owe it and must keep making payments |
There is one situation where the window can be given up voluntarily, and it deserves its own explanation.
Can you waive the right of rescission?
Yes, you can waive the right of rescission if you have a bona fide personal financial emergency. This is the CFPB’s stated standard, and it is narrow.
To waive, you must give the lender your own written statement describing the emergency and clearly stating that you are waiving the right to rescind. Pre-printed forms are not allowed.
The statement must be dated and signed by you and anyone else who shares in the ownership of the home. If you waive, you might lose the right to rescind the transaction unless there is proof of fraud.
Waiving is a serious step, but so is the flip side: sometimes the rescission window is far longer than three days.
When can the rescission window stretch to three years?
In some cases, the right to cancel can extend for up to three years. This can happen if the lender does not give you the Truth in Lending disclosure, which in most cases is the Closing Disclosure, or does not give you two copies of the notice of the right to cancel.
It can also happen if the lender makes certain important mistakes on the Truth in Lending disclosure. These are technical questions about the accuracy of the documents you received.
The CFPB’s guidance is to consult a lawyer right away if you think this extended window may apply to you. Extended rescission is not something to attempt on your own.
Whether your situation is a routine three-day cancellation or a disclosure dispute, it helps to read the primary source yourself.
Where to read the official rules
The authority here is the Consumer Financial Protection Bureau, the federal agency that implements and enforces federal consumer financial law. Its Ask CFPB pages on the right of rescission spell out everything summarized in this article.
If you have a problem with the mortgage closing process, the CFPB says to discuss the issue with your lender first. You can also submit a complaint to the CFPB online or by calling (855) 411-CFPB (2372), and the bureau will forward the complaint to the company and work to get you a response.
You may also want your own attorney to review the situation. The CFPB notes its guidance is general consumer information, not legal advice.
For homeowners here in Colorado, there is one more layer worth thinking through before signing or canceling.
What this means for Colorado Springs homeowners
Colorado Springs is a heavily military market, and refinance decisions often collide with life events like a PCS move. If orders arrive right after a closing and the deal no longer makes sense, the rescission window exists precisely so you can change your mind within those three business days.
The key discipline is the same for everyone: cancel in writing before the midnight deadline, keep a copy, and keep paying the original mortgage without interruption. Rescinding the refinance never pauses the loan you already had.
If you canceled because the numbers or terms surprised you at the closing table, that is worth a conversation, not a retreat. A broker can walk you through refinance options in Colorado and compare structures before you ever sign another Promissory Note.
Military borrowers can also review the VA loan resources on our site as part of that conversation. Better information before closing is what makes rescission unnecessary.
Your next step
If you are inside the three-day window and want out, put your cancellation in writing today, deliver or mail it before midnight of the third business day, and keep a copy. Then confirm your original mortgage payment schedule and stay current on it.
If you are unsure whether the window is still open, whether a disclosure error extends it, or whether canceling is even the right call, talk with a 719 Lending loan officer. We can walk through the closing documents with you, and if the refinance still makes sense on different terms, map out what a restructured loan would look like before you sign anything new.
Frequently asked questions
If I rescind a refinance loan, do I still owe the original loan?
Yes. The CFPB states that the right to rescind does not change your obligation to make payments on your other loans. If you refinance and then rescind the refinance, you still have to pay the original loan because it was never paid off.
How many days do I have to cancel a refinance after closing?
You have three business days to rescind a non-purchase money mortgage such as a refinance. Saturdays count as business days, but Sundays and legal public holidays do not, and the clock does not start until you have signed the Promissory Note, received the accurate Truth in Lending disclosure, and received two copies of the notice of your right to rescind.
Can I rescind a refinance by calling my lender?
No. You must notify the lender in writing, using either the form the lender provided or your own letter. A phone call or an in-person visit does not count as a valid rescission.
How long does the lender have to return my money after I rescind?
Within 20 calendar days after the lender receives your written notice of rescission, all money or property you paid as part of the mortgage transaction must be returned to you.
Can the right of rescission last longer than three days?
In some cases, yes. If the lender failed to give you the Truth in Lending disclosure or two copies of the notice of the right to cancel, or made certain important mistakes on the disclosure, you may have the right to cancel for up to three years. The CFPB recommends consulting a lawyer right away if you think this applies.
Can I waive my right to rescind a refinance?
Yes, but only for a bona fide personal financial emergency. You must give the lender your own written, dated, and signed statement describing the emergency and stating you are waiving the right, signed by everyone who shares ownership of the home. Pre-printed forms are not allowed.
719 Lending Inc., NMLS #1601989 · Equal Housing Opportunity
719 Lending Inc. is not affiliated with or endorsed by HUD, FHA, VA, USDA, CHFA, the CFPB, or any government agency.
Last updated: September 2026

Related Posts