The company you send your monthly mortgage payments to is called your mortgage servicer. It may or may not be the same company as your mortgage lender, and it can change during the life of the loan. Here is how servicing works, what federal rules protect you during a servicing transfer, and what Colorado homeowners should watch for.
What Lenders Do When Home Valuations Differ Significantly
What does my lender do when there are significant differences between valuations? The answer, according to the Consumer Financial Protection Bureau, is direct: your lender has to decide which value is most reliable. This article explains how lenders make that call, why different valuations happen in the first place, and what you as a Colorado buyer or homeowner can do about it.
If you are buying near Fort Carson or Peterson Space Force Base on a tight PCS timeline, or refinancing a home you have owned for years, the valuation process works the same way — and knowing it keeps a confusing moment from derailing your mortgage loan.
The short answer: the lender picks the most reliable value

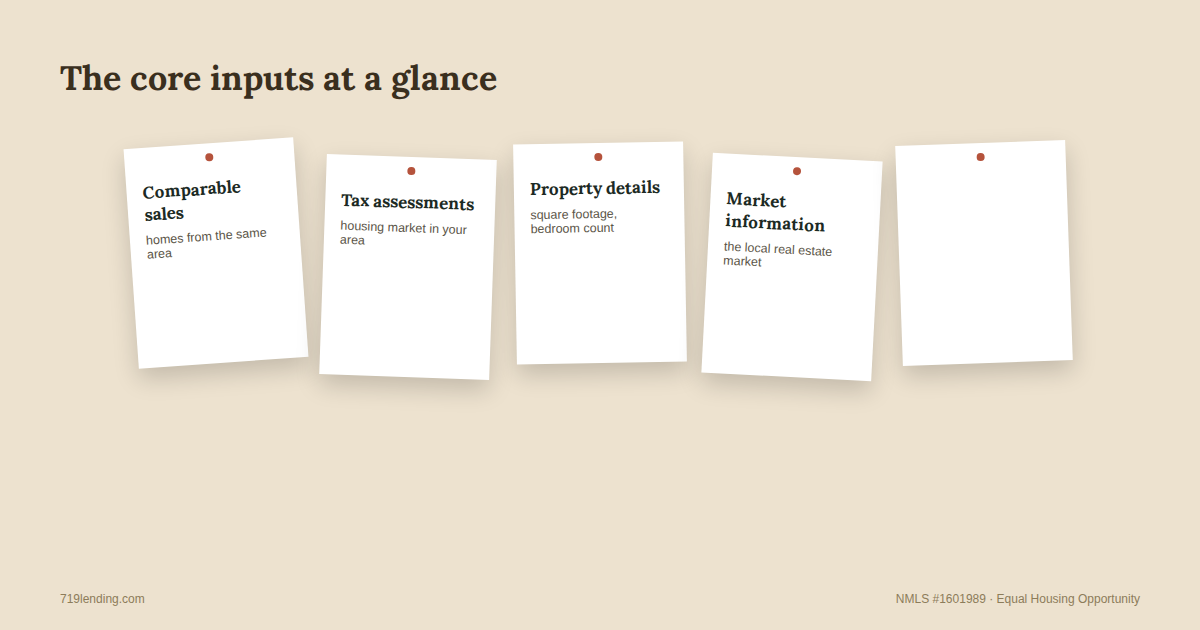
A valuation is an estimate of the amount of money a home may be worth, based on tax assessments and sales information for the housing market in your area. It also reflects details about the home itself — square footage, the number of bedrooms and bathrooms, and the year it was built.
Because every valuation is an estimate, two of them can legitimately disagree. When the gap between them is big, the lender weighs the methods, the comparable sales, and the timing behind each one and decides which value conclusion it will rely on.
No matter which value the lender chooses, it is required to give you copies of each valuation it has. That right is the foundation for everything else in this article.
Before we get to how lenders resolve conflicts, it helps to know what kinds of valuations show up in a file.
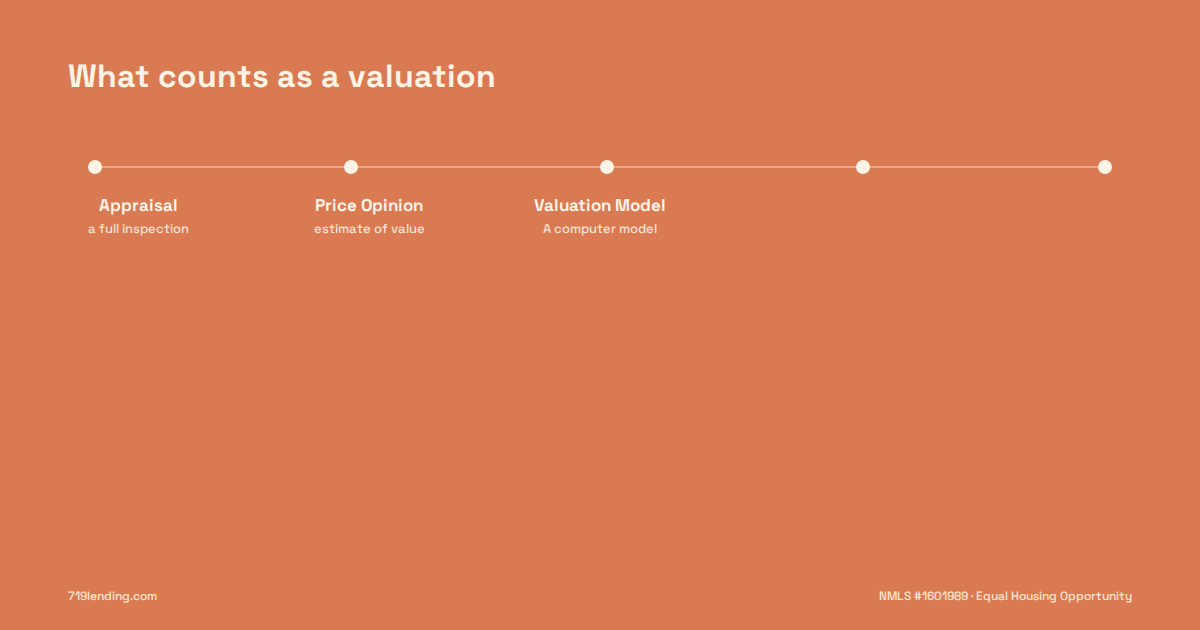
The three types of valuations lenders use
During a purchase or refinance, your lender will get at least one valuation of the property. In practice, a file can contain several, each produced by a different method.
Full appraisal by a licensed appraiser
An appraisal by a licensed real estate appraiser who does a full inspection of the property is the most common type of valuation. The appraiser visits the subject property and prepares an appraisal report.
Appraised value is generally determined by making adjustments between the features of your home and comparable local property sales — called comps for short. If a nearby sale had one more bathroom than your home, the appraiser adjusts for that difference to reach an estimate of market value.
Broker price opinion (BPO)
A broker price opinion is an estimate of value provided by a real estate sales professional. A BPO is most commonly used to justify a home’s listing price.
Because a BPO is prepared by a real estate agent rather than a licensed appraiser, and often for a different purpose, its number can land well away from the appraised value.
Automated valuation model (AVM)
An automated valuation model is a computer-generated value. It uses mathematical models that compare information about the house you want to buy — number of bedrooms, bathrooms, square feet, and so on — with recent sales figures and other information about the housing market in your area.
Your lender may get an AVM when you first submit your loan application, just to make sure the property value is reasonable. Later, the lender may require a full appraisal by a licensed real estate appraiser.
With those three tools on the table, the next question is why they so often disagree.
Why do valuations of the same home come out different?
Each valuation may be different because all of them are estimates. The CFPB points to three specific reasons the numbers diverge.
Different comparable sales
Two valuations may be based on different comps. One appraiser might lean on recent sales in your immediate neighborhood, while an AVM pulls from a wider slice of the local real estate market.
In a market like Colorado Springs, where neighborhoods a few minutes apart can behave very differently, the choice of comparable properties moves the number meaningfully.
Different points in time
Valuations may have been completed at different times. Market conditions shift, and an estimate from early in the lending process can read differently than one completed weeks later, especially in a fast-moving seller’s market.
Different purposes
Valuations are also prepared for different purposes. A BPO exists to support a listing price. An early AVM exists to confirm the property value is reasonable before the lender invests in a full appraisal. A full appraisal exists to give the lender a thorough, inspected estimate of the home’s market value.
Different purpose, different method, different number — which is exactly why the lender has to adjudicate when the gaps get large.
What does my lender do when there are significant differences between valuations?
Here is the core of it, straight from the CFPB: if there is a big difference between the different valuations, your lender will have to decide which value is most reliable.
How the lender weighs reliability
The lender looks at how each valuation was produced. A full appraisal involves a licensed appraiser physically inspecting the property and making line-by-line adjustments against comparable sales, while an AVM never sees the inside of the house.
The lender also considers when each valuation was completed and why it was ordered. An early application-stage AVM serves a different role than the full appraisal report ordered later in the process.
Once the lender settles on the value it considers most reliable, that figure is what the mortgage loan proceeds on. Your loan officer can walk you through which valuation the lender relied on and why.
Your right to copies of every valuation
No matter where the values came from, your lender is required to give you copies of each valuation it has. That includes the appraisal report, any broker price opinion, and any automated valuation model output in the file.
Read them. Seeing which comps each one used, and when each was completed, usually explains the gap better than any summary can.
Knowing how the lender decides is half the picture. The other half is what you can do when the number you get is not the number you hoped for.
What you can do if the appraised value comes in low
The most common pain point is an appraisal gap: the appraised value lands well below the purchase price you agreed to pay. The CFPB names two responses, plus an option to get your own valuation.
Renegotiate the purchase price
If the appraisal is well below the price you offered to pay, you may want to consider renegotiating the home purchase price. The appraisal report gives you and your real estate agent concrete, documented support for that conversation with the seller.
Whether renegotiation is realistic depends on market conditions. In a strong seller’s market, sellers have more leverage; in a cooler one, a documented low appraisal carries real weight.
Review the appraiser’s work carefully
The other response the CFPB suggests is reviewing the appraiser’s work carefully to understand how the appraiser arrived at the estimated value. Look at the comparable sales the appraiser chose and the adjustments made for differences in square footage, bedrooms, bathrooms, and year built.
If you believe the comps misrepresent your home’s market, raise it with your loan officer. Talk through what an appraisal review of the specific report would involve in your situation.
Get your own independent appraisal
You may also get your own independent appraisal, though you might have to pay an additional fee. That gives you a second professional estimate of the property’s market value to compare against the one in the lender’s file.
Keep in mind this adds another valuation to the mix — and the lender still decides which value is most reliable.
One more piece of context helps here: knowing exactly who in the mortgage chain is making these decisions.
Lender, broker, servicer: who actually decides?
The valuation decision belongs to the lender, so it is worth being clear on the roles.
A lender is a financial institution that makes direct loans. When you take out a loan with a lender, you pay them back based on the terms of the loan — and it is the lender that obtains at least one valuation and resolves conflicts between valuations.
A broker does not lend money. You can use a broker, like 719 Lending here in Colorado Springs, to find different lenders or mortgage loans, and when you work with a broker you pay a loan-specific fee for their services. Some financial institutions operate as both lenders and brokers, so ask whether a broker is involved in your transaction.
A mortgage servicer is the company that sends your mortgage statements and handles day-to-day loan management after closing — processing payments, tracking principal and interest, and managing a tax and insurance escrow account if you have one. It is common for a different company to take over servicing after closing; your monthly statement identifies the servicer, and MERS® maintains a servicer identification system if you cannot find one.
In short: the broker shops, the lender decides on the valuation and funds the loan, and the servicer manages payments afterward. Regardless of which structure you use, the CFPB advises shopping around and comparing loan terms, rates, and fees.
Everything above traces back to one official source, and it is worth reading directly.
What the official source says and where to read it
The Consumer Financial Protection Bureau’s Ask CFPB page, “Why did I receive different valuations during the mortgage loan application process?”, is the authority behind this article. It defines the three valuation types, explains why estimates diverge, confirms your right to copies of each valuation, and states that the lender must decide which value is most reliable when there is a big difference.
The CFPB is the federal agency that implements and enforces federal consumer financial law, so its guidance applies to home loans everywhere in Colorado — from a first purchase on the east side of Colorado Springs to a refinance of a long-held home in Pueblo. Note that the CFPB’s content is general consumer information, not legal advice.
With the rules clear, here is what to actually do if you are staring at two numbers that do not match.
Next steps for Colorado borrowers
First, request copies of every valuation in your file if you have not received them. Your lender is required to provide them.
Second, compare them. Note which comparable sales each used, when each was completed, and what purpose each served — appraisal, BPO, or AVM.
Third, if the appraised value sits well below the purchase price, talk with your real estate agent about renegotiating, review the appraisal report carefully, and ask your loan officer how the lender is weighing the conflicting values.
If you are buying or refinancing along the Front Range and want someone to walk through the valuations in your file line by line, reach out to 719 Lending. We work with military families managing PCS moves and first-time buyers across Colorado, and explaining the valuation process is part of the job. If you are just starting out, a purchase pre-qualification conversation is the natural first step.
Frequently asked questions
Why did I receive different valuations during the mortgage loan application process?
Because every valuation is an estimate. Different valuations may be based on different comparable sales, may have been completed at different times, or may have been prepared for different purposes — an appraisal, a broker price opinion, and an automated valuation model each work differently, so their numbers can differ.
What happens if there is a big difference between valuations?
Your lender decides which value is most reliable and proceeds on that value. The lender weighs how each valuation was produced, which comps it used, when it was completed, and why it was ordered.
Do I have the right to see every valuation my lender gets?
Yes. No matter where the values came from, your lender is required to give you copies of each valuation it has — including any appraisal report, broker price opinion, or automated valuation model result.
What can I do if the appraised value is well below the purchase price?
The CFPB suggests considering renegotiating the home purchase price or reviewing the appraiser’s work carefully to understand how the appraiser arrived at the estimated value. You may also get your own independent appraisal, though you might have to pay an additional fee.
What is the difference between an appraisal and an AVM?
An appraisal is performed by a licensed real estate appraiser who does a full inspection of the property and adjusts against comparable local sales. An automated valuation model is computer-generated, comparing home details like bedrooms, bathrooms, and square footage with recent sales figures — no inspection involved.
Does the lender or the mortgage broker decide which valuation to use?
The lender. A lender is the financial institution that makes the loan and obtains at least one valuation; a broker does not lend money but helps you find different lenders or mortgage loans. The lender resolves significant differences between valuations.
719 Lending Inc., NMLS #1601989 · Equal Housing Opportunity
719 Lending Inc. is not affiliated with or endorsed by HUD, FHA, VA, USDA, CHFA, the CFPB, or any government agency.
Last updated: October 2026

Related Posts