The company you send your monthly mortgage payments to is called your mortgage servicer. It may or may not be the same company as your mortgage lender, and it can change during the life of the loan. Here is how servicing works, what federal rules protect you during a servicing transfer, and what Colorado homeowners should watch for.
What Information Does a Home Valuation Take Into Account?
What information does a home valuation take into account? In plain terms, a home valuation compares the property you want to buy or refinance with sales information on similar homes from the same area, layered on top of tax assessments and the physical details of the home itself. This guide walks Colorado buyers and refinancers through exactly what goes into the number, who produces it, and what to do when the result surprises you.
Whether you are buying your first home near one of the Colorado Springs installations or refinancing a property you have owned for years, the mechanics are the same. The Consumer Financial Protection Bureau (CFPB) lays them out clearly, and we will stick to what that official source actually says.
What information does a home valuation take into account?
According to the CFPB, a valuation is an estimate of the amount of money a home may be worth, based on tax assessments and sales information for the housing market in your area.
The valuation is also based on information about the home itself. That includes square footage, the number of bedrooms and bathrooms, and the year the property was built.
In an appraisal, value is generally determined by making adjustments between the features of your home and comparable local property sales — comps for short. The surrounding real estate market does most of the heavy lifting.
So the inputs break into three buckets, which we will unpack one at a time below.
The core inputs at a glance
- Comparable sales: sales information on similar homes from the same area, with adjustments for differences between those comps and your property.
- Tax assessments: assessment data for the housing market in your area feeds into the estimated value.
- Property details: square footage, bedroom count, bathroom count, and the year the home was built.
- Market information: recent sales figures and other information about the local real estate market, especially in computer-generated valuations.

With the inputs defined, the next question is who this actually affects during a real estate transaction.
Who needs to understand home valuations
Home valuations matter to anyone with a mortgage in motion. When you buy or refinance a home, the mortgage lender will get at least one valuation on the property.
That means first-time buyers, move-up buyers, and homeowners refinancing all encounter the home appraisal process. So do sellers, since the appraised value can affect whether a deal closes at the agreed purchase price.
Colorado Springs and military buyers
In a military market like Colorado Springs, PCS timelines compress everything, and the appraisal sits squarely in the middle of the loan process. Understanding what the appraiser is actually measuring helps you read the appraisal report instead of just reacting to the bottom-line number.
It also helps when you are shopping: if the homes selling around your target neighborhood are smaller or older than the one you are offering on, the comps will reflect that. Next, let’s look at the different forms a valuation can take.
The three types of home valuation lenders use
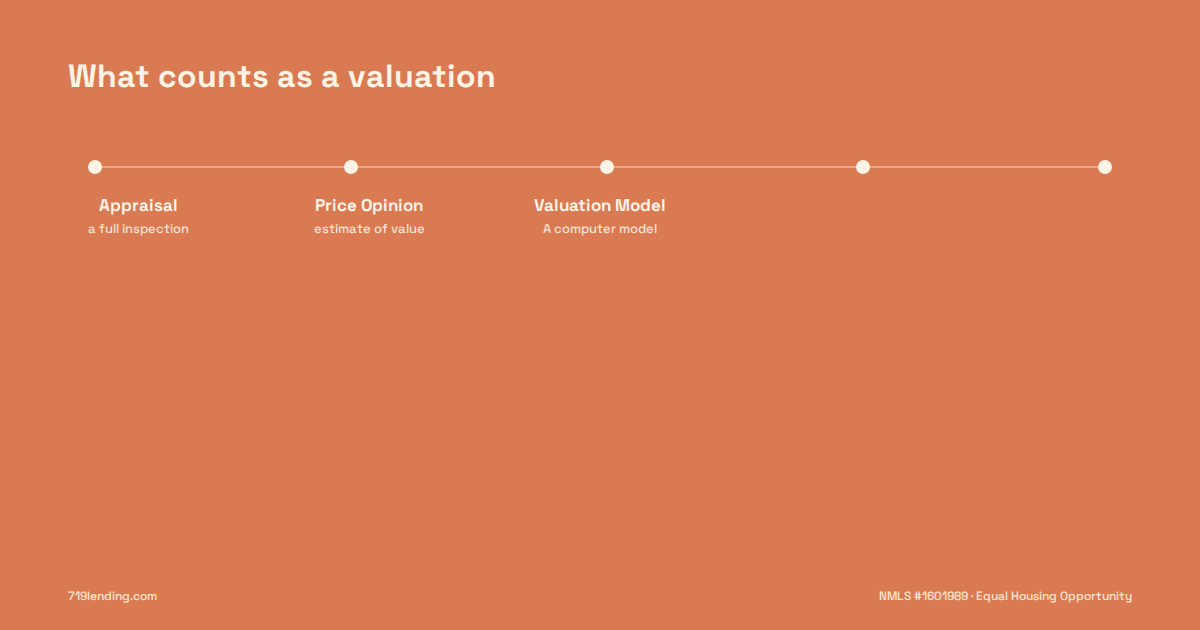
The CFPB identifies three common forms of property valuation. Each one draws on the same kinds of information, but they differ in who produces them and how.
Full appraisal by a licensed appraiser
An appraisal by a licensed real estate appraiser who does a full inspection of the property is the most common type of valuation. When the appraiser visits, they document the home, then determine value by making adjustments between your home’s features and comparable local property sales.
The finished appraisal report shows the comps used and how the appraiser arrived at the estimated value.
Broker price opinion (BPO)
A Broker Price Opinion, or BPO, is an estimate of value provided by a real estate sales professional. Per the CFPB, a BPO is most commonly used to justify a home’s listing price.
A BPO is not the same thing as a full home appraisal, even though both lean on comparable sales in the local market.
Automated valuation model (AVM)
An Automated Valuation Model, or AVM, is a computer-generated value. It uses mathematical models that compare information about the house — number of bedrooms, bathrooms, square feet, and so on — with recent sales figures and other information about the real estate market in your area.
A mortgage lender may run an AVM when you first submit a loan application, just to make sure the property value is reasonable. Later, the lender may still require a full appraisal by a licensed real estate appraiser.
| Valuation type | Who produces it | How it works |
|---|---|---|
| Full appraisal | Licensed real estate appraiser | Full inspection of the property; adjustments against comparable local property sales |
| Broker price opinion (BPO) | Real estate sales professional | Estimate of value, most commonly used to justify a listing price |
| Automated valuation model (AVM) | Computer model | Compares home details with recent sales figures and market information for the area |
Since comps are the engine behind most of these valuations, they deserve a closer look.
How comparable sales drive the appraised value
Comparable sales — comps — are sales of similar homes in the same area as the property being valued. They anchor the valuation to what buyers have actually paid in the local market, not to what anyone hopes the home’s value might be.
What makes a sale a comp
A useful comp is a similar property from the same area with a recorded sale. The closer it matches your home on the details the valuation measures — square footage, bedrooms, bathrooms, year built — the less adjusting the appraiser has to do.
Adjustments between your home and the comps
No two properties are identical, so appraisal values are generally determined by making adjustments between the features of your home and the comparable sales. If a comp is larger or has more bathrooms than your home, the appraiser accounts for that difference when working toward the appraised value.
This adjustment work is why reading the appraisal report matters: you can see which recently sold properties the appraiser relied on and how each one was treated. That also explains the next puzzle — why two valuations on the same property can disagree.
Why you might receive different valuations on the same home
Borrowers are often surprised when an AVM, a BPO, and a full home appraisal land on different numbers for the same property. The CFPB’s answer is straightforward: each of these valuations is an estimate.
Different comps, different times, different purposes
Valuations may be based on different comps, may have been completed at different times, or may have been done for different purposes. A value generated at application and a full appraisal completed later in the loan process are measuring a moving real estate market from different vantage points.
What the lender does when valuations disagree
If there is a big difference between the valuations, the mortgage lender has to decide which value is most reliable. That lender decision — not an average of the estimates — is what carries forward in the home loan file.
Whatever the lender decides, you have a legal right to see every valuation it obtained, which brings us to disclosure.
Your right to copies of every valuation
No matter where the values came from, your lender is required to give you copies of each valuation it has. That includes the full appraisal report, any BPO, and any AVM result tied to your application.
You may also get your own independent appraisal, though the CFPB notes you might have to pay an additional fee for it. Between the lender’s copies and your own review, you should never be guessing at how a home’s appraised value was reached.
Those documents become especially important when the number comes in below the contract price.
What to do if the home appraisal comes in low
A low appraisal is not automatically the end of a real estate transaction. The CFPB outlines two practical responses when the appraisal is well below the price you offered to pay.
Renegotiate the purchase price
First, you may want to consider renegotiating the home purchase price with the seller. In a competitive market, sellers vary in how they respond, but the appraisal gives you a documented basis for the conversation, and your real estate agent can help frame it.
Review the appraiser’s work
Second, you can review the appraiser’s work carefully to understand how the appraiser arrived at the estimated value. Walk through the comps in the appraisal report and the adjustments made for differences between those sales and your property.
If the appraisal still does not support the deal, talk with your loan officer about the options on your specific file before making a decision. It also helps to be clear on what an appraisal is not — which is where the home inspection comes in.
Home appraisal vs. home inspection
A home appraisal and a home inspection happen around the same stage of the loan process, but they answer different questions. The appraisal estimates what the home may be worth for the mortgage lender; the appraiser visits the property and anchors the value in comparable sales and the home’s measurable details.
Both documents are worth reading closely, but only the appraisal determines the value the lender uses.
Value is one question; affordability is a separate one, and the CFPB is direct about not confusing the two.
Appraised value is not the same as what you can afford
The CFPB cautions borrowers to focus on a mortgage that is affordable given their other priorities, not simply the amount they qualify for. Lenders will tell you how much they are willing to loan, but they do not take into account all of your family and financial circumstances.
When you build a budget around a home’s value and the resulting payment, remember the other costs that typically ride along with a monthly mortgage payment: homeowners insurance, property taxes, possibly private mortgage insurance, and homeowners association fees where they apply. There may also be costs for repairs and maintenance.
The CFPB also advises against sacrificing savings to buy a bigger house — emergencies, retirement, and other priorities still need funding after closing. A home that appraises well but strains the budget is not a win, so run both analyses before you commit.
What the official source says and where to read it
Everything in this article about valuation inputs, valuation types, and your disclosure rights comes from the Consumer Financial Protection Bureau’s consumer guidance, last reviewed in mid-2024. You can read the CFPB’s own explanation of why borrowers receive different valuations during the mortgage application process on the CFPB website under its Ask CFPB mortgage resources.
The CFPB is the federal agency that implements and enforces federal consumer financial law, and its guidance is general consumer information rather than legal advice. If a valuation question on your file turns legal — an inherited property, a disputed report — the CFPB points consumers toward attorneys and HUD-approved housing counselors.
With the official framework in hand, here is how to put it to work.
Next steps for Colorado borrowers
If you are buying or refinancing in Colorado Springs or anywhere along the Front Range, start by asking your loan officer which valuations will be ordered on your file and when they land in the timeline. Then exercise the rights you already have.
- Request copies of every valuation the lender obtains — you are entitled to them.
- Read the appraisal report, including the comps and the adjustments behind the appraised value.
- If the number comes in low, discuss renegotiating the purchase price or reviewing the appraiser’s work before walking away.
- Keep the appraised value and your personal budget as two separate questions.
A home valuation is not a mystery once you know its ingredients: comparable sales from the same area, tax assessment data, and the concrete facts of the property itself. Talk through your scenario with a local loan officer at 719 Lending, and go into the appraisal knowing exactly what the number is built from.
Frequently asked questions
What does a home appraiser look at to determine value?
A licensed real estate appraiser does a full inspection of the property, then determines value by making adjustments between your home’s features — square footage, bedrooms, bathrooms, year built — and comparable local property sales, called comps, along with tax assessment and market information for the area.
Why did I get different valuations on the same house?
Per the CFPB, each valuation is an estimate. Different valuations may use different comps, may be completed at different times, or may be done for different purposes. If there is a big difference between them, the lender must decide which value is most reliable.
Am I entitled to a copy of my home appraisal?
Yes. No matter where the values came from, your lender is required to give you copies of each valuation it has — including a full appraisal report, a broker price opinion, or an automated valuation model result.
What happens if the appraisal is lower than the purchase price?
The CFPB suggests considering renegotiating the home purchase price with the seller, or reviewing the appraiser’s work carefully to understand how the appraiser arrived at the estimated value, including which comparable sales were used.
Is a home appraisal the same as a home inspection?
No. A home appraisal estimates the home’s value for the mortgage lender using comparable sales and property details. A home inspection focuses on the condition of the property for the buyer. They serve different purposes in a real estate transaction.
What is an automated valuation model (AVM)?
An AVM is a computer-generated value that uses mathematical models to compare information about the house — bedrooms, bathrooms, square footage — with recent sales figures and other local market information. A lender may use one early in the loan process and still require a full appraisal later.
719 Lending Inc., NMLS #1601989 · Equal Housing Opportunity
719 Lending Inc. is not affiliated with or endorsed by HUD, FHA, VA, USDA, CHFA, the CFPB, or any government agency.
Last updated: October 2026

Related Posts