The company you send your monthly mortgage payments to is called your mortgage servicer. It may or may not be the same company as your mortgage lender, and it can change during the life of the loan. Here is how servicing works, what federal rules protect you during a servicing transfer, and what Colorado homeowners should watch for.
What Am I Entitled to Receive From My Lender on Valuations?
If you are asking what you are entitled to receive from your lender regarding valuations, the short answer is: copies of all of them. The Consumer Financial Protection Bureau (CFPB) is clear that no matter where the values came from, the lender is required to give you copies of each valuation they have on the property.
This article explains what counts as a written valuation, why the estimates often differ from one another, what other disclosures you are entitled to during a real estate transaction, and what to do next. It is written for Colorado buyers and refinancing homeowners, including the many military families moving through Colorado Springs on PCS orders.
What am I entitled to receive from my lender regarding valuations?
When you buy or refinance a home, the lender will get at least one valuation of the property. You are entitled to a copy of every valuation the lender obtains, not just the one they ultimately rely on.
Those valuations could include a full appraisal, a Broker Price Opinion, or a computer-generated Automated Valuation Model. Each is an estimate of what the home may be worth, and each belongs in your hands.
Here is a quick summary of the three valuation types the CFPB describes before we look at each one in detail.
| Valuation type | Who produces it | How it is typically used |
|---|---|---|
| Appraisal | A licensed real estate appraiser who does a full inspection of the property | The most common valuation; values are determined by adjustments against comparable local property sales (comps) |
| Broker Price Opinion (BPO) | A real estate sales professional | Most commonly used to justify a home’s listing price |
| Automated Valuation Model (AVM) | A computer model comparing the home’s features with recent sales figures | Often pulled early, when you first submit the loan application, to confirm the property value is reasonable |

With the overview in place, let’s look at what each valuation actually is and how it is built.
What counts as a valuation on a mortgage loan?
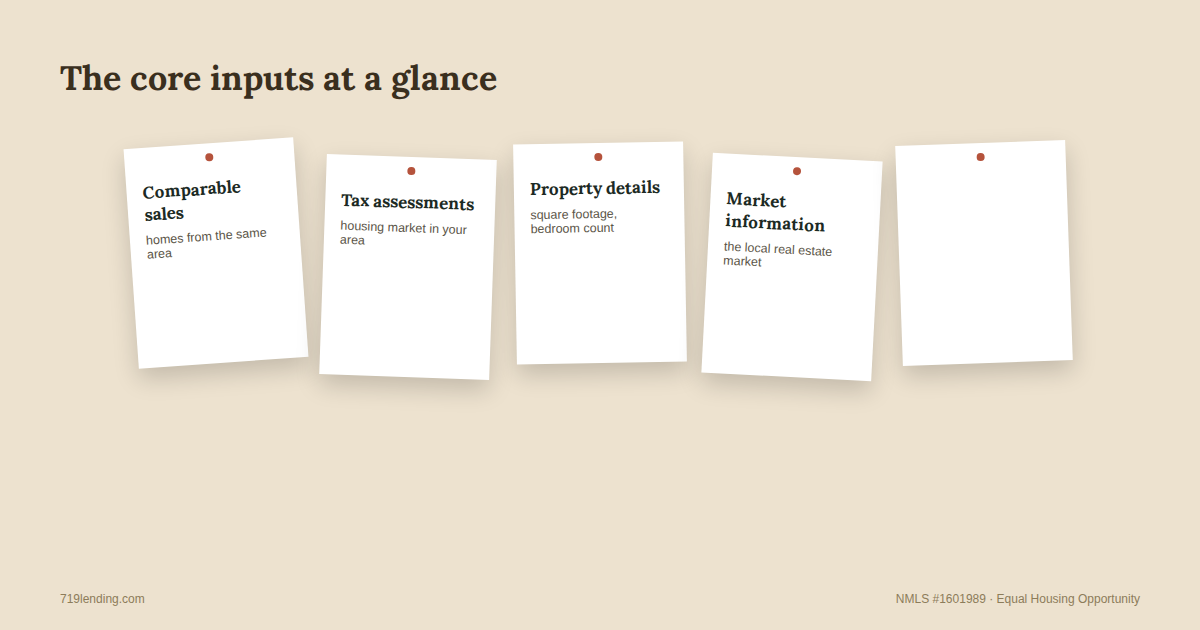
A valuation is an estimate of the amount of money a home may be worth. It is based on tax assessments and sales information for the housing market in your area, plus details about the home itself — square footage, number of bedrooms and bathrooms, and the year it was built.
The full appraisal
An appraisal by a licensed real estate appraiser who performs a full inspection of the property is the most common type of valuation. The appraiser determines value by making adjustments between the features of your home and comparable local property sales, which are called comps.
The appraisal report is the document most buyers think of when they hear valuation, and yes — you have the right to receive a copy of it.
The Broker Price Opinion (BPO)
A Broker Price Opinion is an estimate of value provided by a real estate sales professional. A BPO is most commonly used to justify a home’s listing price, which is why real estate agents are often the ones producing them.
The Automated Valuation Model (AVM)
An Automated Valuation Model is a computer-generated value. It uses mathematical models that compare information about the house you want to buy — bedrooms, bathrooms, square feet — with recent sales figures and other data about the local housing market.
A lender may run an AVM when you first submit the mortgage application just to make sure the property value is reasonable. Later, the lender may require a full appraisal by a licensed real estate appraiser.
Since more than one valuation can exist on the same property, the natural next question is why they rarely match.
Why did I receive different valuations on the same property?
Every valuation compares the home you are trying to buy or refinance with sales information on similar homes from the same area. Because they are estimates, each one can land in a different place.
The CFPB points to three reasons the numbers diverge: the valuations may be based on different comps, they may have been completed at different times, or they may have been prepared for different purposes.
That matters in a market like Colorado Springs, where neighborhoods near Fort Carson or Peterson Space Force Base can see sales activity shift as PCS season turns over the housing inventory. An AVM pulled early in the process and an appraisal completed weeks later may simply be reading different snapshots of the same market.
If there is a big difference between the valuations, the lender has to decide which value is most reliable. Your job is simpler: collect your copies and read them, which leads to who these rights actually cover.
Who does this apply to?
The right to copies of each valuation applies when you buy or refinance a home. Purchase buyers and refinancing homeowners alike should expect at least one valuation on the transaction, and copies of every valuation the lender holds.
For military borrowers in Colorado, this is worth flagging during a PCS move. When you are closing from a distance, ask the loan officer early how valuation copies will be delivered so nothing gets lost between duty stations.
You may also get your own independent appraisal, though you might have to pay an additional fee. That is your option, not a requirement — and it sits alongside the valuations the lender orders, not in place of them.
Valuations are only one category of document you are entitled to. The other big one is the Loan Estimate.
What else am I entitled to: the Loan Estimate
Lenders are legally required to provide you with a Loan Estimate once you have provided six pieces of information. The Loan Estimate lays out the loan terms the lender expects to offer — including the loan amount, the interest rate on the loan, and estimated closing costs — if you decide to move forward.
The six pieces of information
To trigger a Loan Estimate, you provide: your name, your income, your Social Security number (so the lender can pull a credit report), the property address, an estimate of the value of the property, and the desired loan amount.
Notice that an estimate of the property’s value is one of the six. Your own estimate starts the process; the lender’s valuations come later to confirm it.
Lenders cannot require you to provide additional information before issuing a Loan Estimate. You do not have to hand over a home purchase agreement or documents verifying your income first — though sharing more detail about your finances, the property, and the loan type you want usually makes the Loan Estimate more accurate.
The three-business-day clock
Once you have submitted those six items, each lender is required to send the Loan Estimate within three business days. Allow a few extra days if the lender uses postal mail.
If you have not received a Loan Estimate within that timeframe, call the lender and ask why. Receiving the Loan Estimate does not mean the loan is approved or denied — it shows the expected loan terms so you can compare lenders before the loan closes.
Loans that work differently
You will not receive a Loan Estimate or Closing Disclosure if you are shopping for a reverse mortgage, a home equity line of credit (HELOC), a manufactured housing or mobile home loan not secured by real estate, or a subordinate loan through certain types of homebuyer assistance programs.
For those loans, you should receive Truth-in-Lending disclosures instead. A reverse mortgage also comes with a Good Faith Estimate (GFE) and a HUD-1 Settlement Statement rather than the standard Closing Disclosure.
Knowing which documents apply to your loan type keeps you from waiting on a Closing Disclosure that was never coming. Now, where do these rules actually come from?
What the official source says and where to read it
The rules in this article come from the Consumer Financial Protection Bureau, the federal agency that implements and enforces federal consumer financial law and works to keep markets for consumer financial products transparent, fair, and competitive.
The CFPB’s Ask CFPB library answers these questions directly, including “Why did I receive different valuations during the mortgage loan application process?” and “What information do I have to provide a lender in order to receive a Loan Estimate?” Both are free to read at consumerfinance.gov.
The CFPB notes its content is general consumer information, not legal advice. For how any of this affects taxes — including questions about tax deductions tied to a home purchase — tax treatment varies, so talk to a tax professional.
One more entitlement worth knowing involves what a lender can ask about your income.
A related right: income you choose not to disclose
A lender or broker may ask whether income stated in your application comes from alimony, child support, or separate maintenance payments. In general, you only disclose that income if you want the creditor to consider it as part of the application.
The lender or broker must tell you that you do not have to reveal such income if you do not want it considered. That is a disclosure you are entitled to receive, just like the valuation copies.
So what should you do with all of this between now and closing?
What to do if the appraisal comes in low
If the appraisal is well below the purchase price you offered to pay, the CFPB suggests two paths: consider renegotiating the home purchase price, or review the appraiser’s work carefully to understand how the appraiser arrived at the estimated value.
Reading the appraisal report means checking the comps the appraiser selected and the adjustments made between those sales and your property. If the comps look off for the neighborhood, that is a conversation to have with the loan officer and your real estate agent.
With that playbook in hand, here is the concrete next step.
Your next step
Ask the loan officer, in writing, for copies of every valuation on your file — the appraisal, any BPO, and any AVM the lender ran. You are entitled to all of them, and reading them side by side tells you how the lender sees the property.
If you are early in the process, gather the six pieces of information and request a Loan Estimate from more than one lender so you can compare loan costs, closing costs, and loan terms on equal footing. The 719 Lending team in Colorado Springs can walk you through each valuation on your file and what it means for the transaction — whether you are buying your first home near a local installation or refinancing one you already own.
Frequently asked questions
Do I have the right to receive a copy of my home appraisal?
Yes. When you buy or refinance a home, the lender is required to give you copies of each valuation they have, including the full appraisal report, any Broker Price Opinion, and any Automated Valuation Model.
Why did I receive different valuations during the mortgage loan application process?
Valuations are estimates. They may be based on different comparable sales, completed at different times, or prepared for different purposes. If there is a big difference between them, the lender must decide which value is most reliable.
What is an Automated Valuation Model (AVM)?
An AVM is a computer-generated value that uses mathematical models to compare the home’s features — bedrooms, bathrooms, square footage — with recent sales figures and other local housing market data. Lenders may run one early in the application, then require a full appraisal later.
How quickly must a lender send me a Loan Estimate?
Once you provide six pieces of information — name, income, Social Security number, property address, an estimate of the property’s value, and the desired loan amount — each lender must send a Loan Estimate within three business days.
Do I have to provide a purchase contract to get a Loan Estimate?
No. Lenders cannot require additional information beyond the six items. You do not have to provide a home purchase agreement or income verification documents to receive a Loan Estimate, though sharing more detail can make the estimate more accurate.
What should I do if the appraisal is below the price I offered?
The CFPB suggests considering renegotiating the home purchase price, or reviewing the appraiser’s work carefully to understand how the appraiser arrived at the estimated value, including which comparable sales were used.
719 Lending Inc., NMLS #1601989 · Equal Housing Opportunity
719 Lending Inc. is not affiliated with or endorsed by HUD, FHA, VA, USDA, CHFA, the CFPB, or any government agency.
Last updated: October 2026

Related Posts