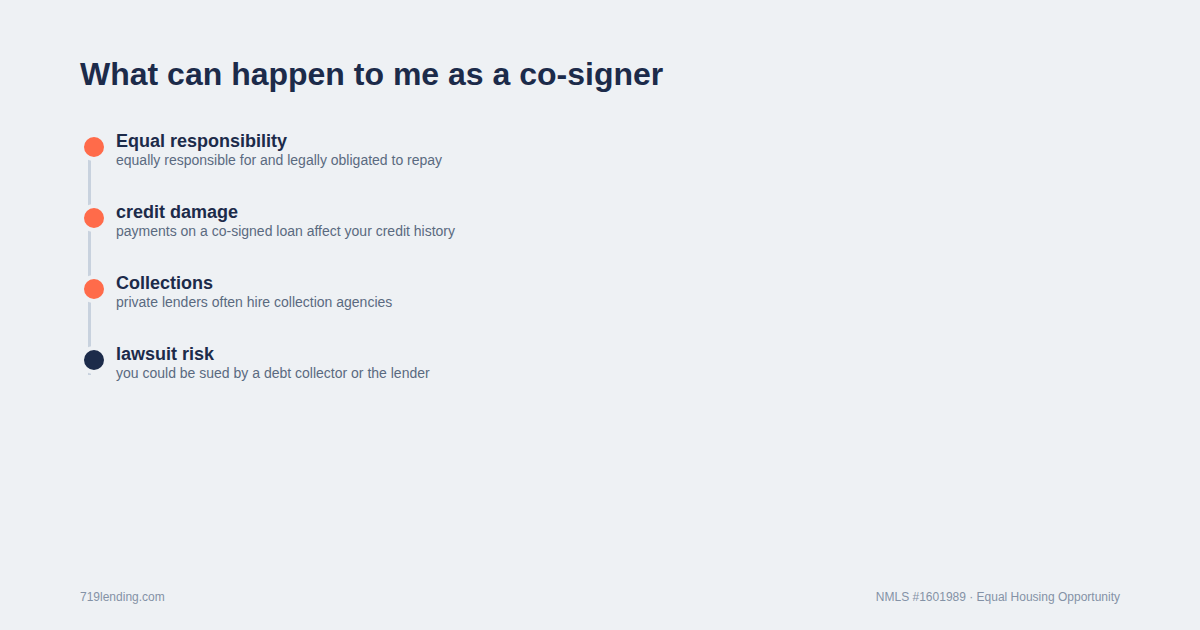
Cosigning a loan means you are equally responsible for the debt. If the primary borrower defaults, the lender can report the missed payments on your credit, send a collection agency after you, and even sue you. Here is exactly what can happen, what the Consumer Financial Protection Bureau says, and what to do before things get that far.
Relief Options for Homeowners With Mortgage Problems
What relief options are available for homeowners with mortgage problems? According to the Consumer Financial Protection Bureau (CFPB), borrowers who cannot make their mortgage payments may be offered a refinance, a loan modification, a repayment plan, forbearance, a short sale, or a deed-in-lieu of foreclosure — and free foreclosure prevention help is available through HUD-approved housing counselors.
This guide walks Colorado homeowners through the exact sequence: who to call first, what to say, which loss mitigation options exist, and how to avoid foreclosure prevention companies that charge for help you can get at no cost.
Here is the short list of relief options the CFPB says a mortgage servicer might make available:
- Refinance the loan
- Get a loan modification
- Work out a repayment plan
- Get forbearance
- Short-sell the home
- Give the home back to the lender through a deed-in-lieu of foreclosure
What relief options are available for homeowners with mortgage problems?
Relief starts with one phone call. The CFPB’s guidance is direct: if you can’t pay your mortgage or are worried about missing a mortgage payment, call your mortgage servicer right away.

Many mortgage servicers have programs designed to help people avoid foreclosure. The servicer reviews your situation, considers which options could be available, and tells you what loss mitigation options, if any, it can offer.
Alongside the servicer, a HUD-approved housing counseling agency provides free, expert assistance on avoiding foreclosure. You do not have to face the process alone, and you do not have to pay anyone for this help.
The next sections explain who this applies to and how each step works in practice.
Who these mortgage relief options apply to
Mortgage relief options apply to any homeowner having trouble paying a mortgage loan — whether the financial hardship is temporary, like a gap between jobs, or permanent, like a lasting drop in income.
The CFPB specifically calls out servicemembers who have received permanent change of station (PCS) orders. A military move matters, because PCS orders could qualify you for loss mitigation options you would not otherwise be offered.
That detail hits home in Colorado Springs, where PCS season routinely forces families to deal with a mortgage on a house they are leaving. If orders are part of your situation, say so when you call the servicer.
Homeowners with a reverse mortgage loan are covered too: the CFPB notes that HUD-approved housing counseling agencies can discuss options, which may include forbearance or a modified payment program.
Whoever you are, the process begins the same way — with the mortgage servicer.
Step one: call your mortgage servicer
Your mortgage servicer is the company you send mortgage payments to, which is not always the same as the original mortgage lender. The servicer’s phone number appears on the monthly mortgage loan statement, in the coupon book from the lender, or on the servicer’s website.
If you do not know the name of your mortgage servicer, a HUD-approved housing counseling agency can help you find it.
What to have ready for the call
When you call the mortgage servicer, the CFPB says to be prepared to explain:
- Why you are unable to make your payment
- Whether the problem is temporary or permanent
- Details about your income, expenses, and other assets like cash in the bank
- Whether you are a servicemember with PCS orders
Honest, specific answers matter. The servicer uses this picture of your financial situation to decide which foreclosure prevention options fit.
The mortgage assistance application
If the servicer gives you a mortgage assistance application, fill it out. The servicer assesses that application, considers the options that could be available to you, and tells you what loss mitigation help, if any, it can offer.
While the servicer reviews your file, the second call to make is to a housing counselor.
Step two: contact a HUD-approved housing counseling agency
A HUD-approved housing counseling agency is approved by the U.S. Department of Housing and Urban Development to help homeowners who are having trouble paying a mortgage loan. The CFPB recommends contacting one to get free, expert assistance on avoiding foreclosure.
What housing counselors do
According to the CFPB, housing counselors can:
- Discuss your situation and whether you qualify for any programs or additional help
- Help you understand the loss mitigation options your servicer offers and which might work best for you
- Guide you through the process of working with your servicer, other programs, and the paperwork
- Help at little or no cost with budgeting, credit card debt, or other money problems making it hard to pay the mortgage
How to reach one
You can look up a HUD-approved housing counseling agency in your area through HUD, or call the HOPE Hotline, which operates around the clock, every day of the week.
This is a key point the CFPB repeats: you don’t have to pay anyone to help you avoid foreclosure. The help you need is available at no cost from your servicer or through a HUD-approved housing counseling agency.
Now, the options themselves.
The loss mitigation options a servicer may offer
Loss mitigation is the industry term for the menu of alternatives to foreclosure. The CFPB lists the options a mortgage servicer might make available:
| Option | What it means for the homeowner |
|---|---|
| Refinance | Replace the current mortgage loan with a new one |
| Loan modification | The servicer changes the terms of the existing mortgage |
| Repayment plan | Work out a schedule to catch up on missed payments |
| Forbearance | Temporary relief on mortgage payments during a hardship |
| Short sale | Sell the home with the servicer’s involvement |
| Deed-in-lieu of foreclosure | Give the home back to the lender voluntarily |
Which options appear on your menu is the servicer’s call, based on your application and your circumstances. A housing counselor can help you figure out which available options may work best for you.
Options that keep you in the home
A refinance, a loan modification, a repayment plan, and forbearance are all paths that can keep you in the house. If your hardship is behind you and the loan is current, you can also explore a refinance of your current mortgage to restructure the payment going forward.
Options that end the mortgage without a foreclosure
A short sale and a deed-in-lieu of foreclosure both end your ownership, but they are negotiated exits rather than a forced foreclosure. These are typically discussed when the hardship is permanent and keeping the home is not realistic.
Whatever path you consider, one danger runs alongside all of them: scams.
How to avoid foreclosure prevention companies and loan modification scams
Mortgage loan modification scams are schemes to take your money, often by making a false promise of saving you from foreclosure. Because legitimate foreclosure prevention help is free, anyone demanding payment upfront is a red flag by definition.
Warning signs the CFPB lists
- You’re asked to pay upfront for help
- The company guarantees it will get the terms of the mortgage changed, or guarantees you won’t lose your home
- You’re asked to sign over title to your home, or to sign papers you don’t understand
- You’re instructed to send mortgage payments to someone other than your mortgage company or servicer
- You’re told to stop paying the mortgage altogether
- The company offers to do a “forensic audit”
- The company claims government affiliation or uses a logo that looks like a government seal but is slightly different
What a mortgage relief company must provide before charging you
Under the rules the CFPB describes, mortgage relief companies are not allowed to collect any fees until they have given you:
- A written offer from your lender or servicer that you decide is acceptable
- A written document from the lender or servicer describing the key changes to the mortgage if you accept
- A reminder that you have the right to reject the offer without any charge
How to report a scam
If a company has made any of these requests or claims, you can report it by submitting a complaint with the CFPB online or by phone. You can also contact the state attorney general’s office to learn about state protections and file a complaint.
Beyond counselors and regulators, there is one more layer of support worth knowing.
Where to get free legal services and more help
If you are facing imminent foreclosure or have been served with legal papers, the CFPB says you might also need to consult an attorney.
If you think you’ve been the victim of a loan modification scam, an attorney is also the right call.
Servicemembers have an additional door: the local Legal Assistance Office. For military homeowners around Colorado Springs, that is a built-in resource worth using before signing anything you do not fully understand.
All of this traces back to official guidance you can read yourself.
What the official source says and where to read it
The guidance in this article comes from the Consumer Financial Protection Bureau, the federal agency that implements and enforces consumer financial law. Its Ask CFPB pages “If I can’t pay my mortgage loan, what are my options?” and “What are mortgage loan modification scams?” lay out the steps, the loss mitigation options, and the scam warning signs covered here.
The CFPB also publishes a checklist with more information on how to avoid foreclosure, and HUD maintains the directory of approved housing counseling agencies.
Reading the source directly is worthwhile — it is plain-English and free, and it is the same playbook housing counselors work from.
Your next step
If you are behind on mortgage payments or see trouble coming, call your mortgage servicer today, then contact a HUD-approved housing counseling agency for free guidance on your options. Do not pay anyone upfront for foreclosure prevention help.
If your hardship has passed and you are exploring whether restructuring the loan makes sense, the team at 719 Lending can walk through the loan programs available to Colorado homeowners and what a refinance would involve. Reach out to a 719 Lending loan officer to talk through your situation — no pressure, no upfront fees for a conversation.
Frequently asked questions
What should I do first if I can’t pay my mortgage?
Call your mortgage servicer right away. The phone number is on your monthly mortgage statement, in the loan coupon book, or on the servicer’s website. Be ready to explain why you can’t pay, whether the problem is temporary or permanent, and details about your income, expenses, and assets. Then contact a HUD-approved housing counseling agency for free guidance.
What loss mitigation options can a mortgage servicer offer?
According to the CFPB, a servicer might offer a refinance, a loan modification, a repayment plan, forbearance, a short sale, or a deed-in-lieu of foreclosure. The servicer assesses your mortgage assistance application and tells you which options, if any, it can offer.
Do I have to pay for foreclosure prevention help?
No. The CFPB states you don’t have to pay anyone to help you avoid foreclosure. The help you need is available at no cost from your mortgage servicer or through a HUD-approved housing counseling agency. A demand for upfront payment is a scam warning sign.
How do I spot a mortgage loan modification scam?
Warning signs include upfront fees, guarantees that your mortgage terms will change or that you won’t lose your home, requests to sign over title or sign papers you don’t understand, instructions to pay someone other than your servicer, offers of a ‘forensic audit,’ telling you to stop paying the mortgage, or fake claims of government affiliation.
Do PCS orders affect my mortgage relief options?
Yes. The CFPB says servicemembers should tell their mortgage servicer about permanent change of station (PCS) orders, because a military move could qualify you for loss mitigation options. Servicemembers can also get help from their local Legal Assistance Office.
Can I get mortgage help if I have a reverse mortgage?
Yes. HUD-approved housing counseling agencies can discuss options with homeowners having trouble with a reverse mortgage loan, which may include forbearance or a modified payment program.
719 Lending Inc., NMLS #1601989 · Equal Housing Opportunity
719 Lending Inc. is not affiliated with or endorsed by HUD, FHA, VA, USDA, CHFA, the CFPB, or any government agency.
Last updated: October 2026

Related Posts