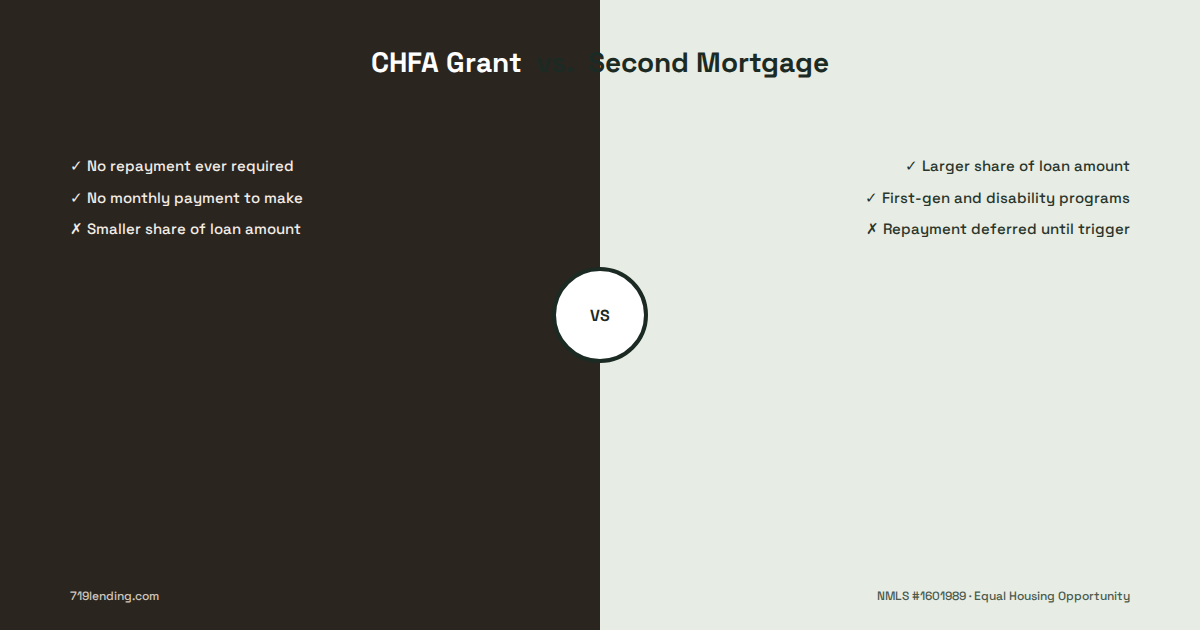
CHFA offers two ways to help Colorado homebuyers with down payment and closing costs: a grant that never has to be repaid, and a deferred second mortgage that is repaid later. Here is how the two structures actually differ, how repayment works, and how a Colorado Springs buyer decides between them.
Do I Have to Take a Homebuyer Education Class for a CHFA Loan?
Do I have to take a homebuyer education class for a CHFA loan? Yes — completing a CHFA-approved homebuyer education class before closing is a firm requirement for every borrower on a Colorado Housing and Finance Authority (CHFA) purchase loan. This guide explains exactly what the class involves, who has to take it, when to take it, and how to make sure the certificate never holds up a closing.
It’s written for Colorado buyers — including the many military families around Colorado Springs — who are looking at CHFA programs for the first time.
Do I have to take a homebuyer education class for a CHFA loan?
Yes. CHFA requires that borrowers individually and independently complete a CHFA-approved homebuyer education class prior to their mortgage loan closing date.
This isn’t a suggestion or a box some lenders check and others skip. It applies to CHFA purchase loans across the board, whether or not you’re also using CHFA down payment assistance.
The one carve-out CHFA states directly: the class requirement does not apply to CHFA refinance programs. If you’re refinancing rather than buying, the education class is not part of the process.
Here’s a quick summary of how the two class formats compare before we go deeper.
| Feature | In-person class | Online class |
|---|---|---|
| Cost | Free | Paid (fee set through the education provider) |
| Format | Live course, averaging six hours | Self-paced course, averaging six hours |
| Extra step | None — certificate issued after class | Required follow-up call with the education provider |
| Languages | English and Spanish; translation and ASL by request | English and Spanish |
| Who issues the certificate | The education provider (not CHFA) | The education provider (not CHFA) |
With the basics on the table, let’s look at why CHFA built this requirement into its programs in the first place.
Why does CHFA require homebuyer education?
CHFA’s stated mission is responsible, affordable homeownership — and the education class is how the agency makes sure borrowers walk into closing informed rather than surprised.
According to CHFA, the class covers how to create a budget as a homeowner, how credit affects your homebuying options and how to improve it, how to find a real estate agent and a lender, the costs of homebuying and the approval process, and what to expect after closing.
In other words, it’s a plain-language walkthrough of the entire journey — from credit report to closing costs to life after you get the keys.
For first-time buyers, that’s genuinely useful ground to cover before you’re under contract and the clock is running. Next, the practical question: where and how do you actually take the class?
What are my options for taking the CHFA class?

CHFA-approved homebuyer education is offered statewide through approved education providers, with both in-person and online formats available in English and in Spanish.
In-person classes
The in-person option is a free, live course averaging six hours. Classes are offered through providers across Colorado, and CHFA’s website has a county-by-county map to help you find one near you — including options in the Colorado Springs area.
All in-person classes are held in facilities accessible for individuals with disabilities. If you need language translation or ASL services, contact the education provider directly to arrange them.
When you finish, the education provider — not CHFA — issues your certificate of completion. You give that certificate to your lender for the loan file.
Online classes
The online option is a self-paced course, also averaging six hours, offered through CHFA’s education providers for a fee. When you register, you pick an education provider — note which one you chose, because you’ll deal with them again.
Here’s the step people miss: online participants are required to complete a follow-up call with the education provider that delivered their class. After the course, you contact the provider to schedule that call, and only after the call does the provider send your certificate.
CHFA specifically warns not to wait on scheduling that follow-up call, because delays there can delay or postpone your closing. Which brings us to timing.
When should I take the homebuyer education class?
Early. CHFA recommends taking the class early in your housing search — before you’re deep into showings, and ideally before you’re under contract.
The reasoning is practical. The class helps you prepare to choose a lender and a real estate agent who fit your situation, so taking it first means you shop smarter from day one.
The hard deadline is closing: the class must be completed before your mortgage loan closing date. Waiting until the last minute is how borrowers turn a routine requirement into a closing delay.
How long is the certificate valid?
Certificates of completion are valid for twelve months. To use the certificate, you must be under contract to purchase a home before it expires.
That’s a generous window — long enough to take the class at the very start of your search and still have plenty of runway. If your search stretches past the certificate’s expiration without a contract, you’d need to complete the class again, so timing matters at both ends.
Now for the detail that surprises couples and co-borrowers most.
Does every borrower have to take the class, or just one of us?
Every borrower. CHFA requires that each borrower on the loan individually and independently register for and complete a CHFA-approved class.
Each borrower must also obtain their own certificate of completion. One spouse’s certificate doesn’t cover the other; a co-borrower parent needs their own certificate too.
You don’t have to take the same class at the same time — you can each choose the format and schedule that works. But every name on the loan needs a certificate in the file before closing.
Once everyone has completed the class, here’s how the paperwork flows.
What happens after I finish the class?
The education provider issues your certificate of completion. Note that the certificate comes from the provider, not from CHFA itself — a common point of confusion when borrowers wait for something from CHFA that isn’t coming.
For in-person classes, the certificate comes after you complete the live session. For online classes, it comes after your required follow-up call with the provider.
You then deliver the certificate to your lender so it can go in your loan file. Your loan officer at a CHFA Participating Lender tracks this as part of the closing checklist, but you’re the one who has to complete the class and hand over the document.
The class is one requirement among several, so it’s worth seeing where it fits in the bigger picture.
What else does CHFA require besides the class?
Homebuyer education is one of CHFA’s general purchase-loan requirements. The others, as CHFA lists them, include:
- A mid-credit score at or above the threshold CHFA sets — your loan officer confirms the current requirement against your credit report
- Income at or below CHFA’s income limits, which vary and are verified by your lender
- A minimum borrower financial contribution toward the purchase, in an amount CHFA specifies
- Completion of the CHFA-approved homebuyer education class by every borrower before closing
On top of CHFA’s rules, you still have to qualify under the underwriting guidelines of the CHFA Participating Lender you choose. CHFA is clear that it does not qualify homebuyers or lend money directly to consumers — approved lenders handle qualification and make the loans.
That’s also why questions about your specific situation — debt-to-income ratio, credit report issues, income documentation — go to a Participating Lender rather than to CHFA. As a Colorado Springs mortgage broker, 719 Lending works with CHFA loan programs and can walk you through which requirements apply to you.
The class also unlocks more than just the first mortgage.
Does the class requirement apply if I’m using down payment assistance?
Yes — and it’s worth taking either way. Buyers using a CHFA first mortgage are eligible to pair it with CHFA assistance for down payment and/or closing costs, offered as a grant with no repayment required or as a second mortgage loan with repayment deferred until events like payoff of the first mortgage, sale or refinance of the home, or the home no longer being your primary residence.
The homebuyer education requirement rides along with the first mortgage, so whether or not you add assistance, the class still has to be done before closing.
If you’re weighing the grant against the second mortgage, our breakdown of CHFA down payment assistance options covers how the two structures differ.
Before you register, a few pitfalls are worth knowing about.
What can go wrong with the class requirement?
Waiting too long to take it
The most common mistake is treating the class as an end-of-process errand. If you’re under contract with a tight closing date and haven’t started the class, you’re gambling with your timeline — CHFA itself warns that waiting may delay or postpone your closing.
Skipping the online follow-up call
Online students sometimes finish the course and assume they’re done. The certificate doesn’t come until after the follow-up call with the education provider, so schedule it immediately after finishing the course.
Only one borrower taking the class
Every borrower needs their own certificate. Discovering at the eleventh hour that a co-borrower never registered is a fixable problem — but not a fun one on a deadline.
Letting the certificate expire
Certificates last twelve months, and you must be under contract before yours expires. If a long search runs past that window, plan to retake the class.
For military buyers around Colorado Springs, timing deserves extra attention.
A note for military buyers near Colorado Springs
PCS timelines rarely cooperate with homebuying timelines. If you’re moving to Fort Carson, Peterson Space Force Base, Schriever, or the Air Force Academy and considering a CHFA program, the online class format means you can knock out the education requirement before you ever arrive in Colorado.
Take the class during the PCS planning window, keep the certificate handy, and you’ll have twelve months to get under contract — plenty of room even for a house hunt squeezed around a report date.
Service members also comparing a VA loan against a CHFA program should talk through both paths with a loan officer, since the education class applies to the CHFA side of that comparison.
Your next step
If a CHFA loan is on your shortlist, register for a CHFA-approved homebuyer education class now, before you get deep into your search. Choose in-person if you want a free, live format, or online if you need scheduling flexibility — and if you go online, book the follow-up call the day you finish.
Then connect with a CHFA Participating Lender to confirm which programs and requirements fit your situation. Reach out to the 719 Lending team and we’ll map out the CHFA process — class, certificate, and all — from application to closing.
Frequently asked questions
Is the homebuyer education class required for a CHFA loan?
Yes. Every borrower on a CHFA purchase loan must individually complete a CHFA-approved homebuyer education class before the mortgage loan closing date. The requirement does not apply to CHFA refinance programs.
Does each borrower have to take the CHFA class separately?
Yes. CHFA requires each borrower to individually and independently register for and complete a class, and each borrower must obtain their own certificate of completion. One certificate cannot cover two borrowers.
How long is the CHFA homebuyer education certificate good for?
Certificates are valid for twelve months. You must be under contract to purchase a home before the certificate expires, so CHFA recommends taking the class early in your housing search.
Is the CHFA homebuyer class free?
In-person classes are free, live courses averaging six hours. The online, self-paced option carries a fee paid through the education provider and requires a follow-up call with that provider before the certificate is issued.
Can I take the CHFA homebuyer education class online?
Yes. CHFA offers a self-paced online class through its approved education providers, available in English and Spanish. After finishing the course, you must complete a follow-up call with your provider, who then sends your certificate.
Who gives me the certificate after the CHFA class?
The education provider issues the certificate of completion — not CHFA. You then give the certificate to your lender so it can be placed in your loan file before closing.
719 Lending Inc., NMLS #1601989 · Equal Housing Opportunity
719 Lending Inc. is not affiliated with or endorsed by HUD, FHA, VA, USDA, CHFA, the CFPB, or any government agency.
Last updated: September 2026

Related Posts