CHFA loan servicing is handled through a servicing alliance between the Colorado Housing and Finance Authority and Dovenmuehle Mortgage, Inc. Here is how payments, hardship assistance, insurance changes, payoffs, and account questions actually work after closing on a CHFA loan.
What Will a CHFA Loan Officer Help Me With? A Colorado Guide
If you are asking what a CHFA loan officer will help you with, here is the direct answer: a loan officer at a CHFA Participating Lender helps you figure out which Colorado Housing and Finance Authority (CHFA) loan programs fit your situation, then walks you through the entire loan process from application to closing. This guide is for Colorado homebuyers, including the many military families around Colorado Springs, who want to understand exactly what this person does before picking up the phone.
At a glance, a CHFA loan officer helps with:
- Determining which CHFA loan programs will work for you
- Explaining home purchase and refinance loan program options
- Coordinating grants and second mortgage loans for down payment and/or closing cost assistance
- Reviewing CHFA’s general program requirements against your file
- Confirming the homebuyer education class requirement and collecting your certificate
- Qualifying you under their lender’s underwriting guidelines
- Guiding you from application all the way to closing
What will a CHFA loan officer help me with, exactly?

CHFA’s own guidance is plain: a loan officer working for a CHFA Participating Lender can help you determine which CHFA loan programs will work for you, and they will walk you through the entire loan process from application to closing.
That sentence carries more weight than it first appears. CHFA does not lend money directly to consumers. The agency uses approved lenders to qualify customers and make all mortgage loans.
So the loan officer is not a nice-to-have. The loan officer is the only door into a CHFA loan.
Understanding that structure explains everything else the loan officer does for you, which is where we go next.
Why can’t I get a CHFA loan from CHFA directly?
The Colorado Housing and Finance Authority operates through a statewide network of CHFA Participating Lenders. CHFA sets the programs; the Participating Lenders take applications, qualify borrowers, and make the loans.
CHFA also does not qualify homebuyers. Any questions about your potential qualifications get discussed with a CHFA Participating Lender, not with the agency itself.
That means the loan officer sits at the intersection of two rulebooks: CHFA’s program requirements and the lender’s own underwriting guidelines. You must satisfy both.
With the structure clear, let’s look at the first concrete job the loan officer does: matching you to a program.
Matching you to the right CHFA program
Through its Participating Lenders, CHFA offers home purchase and refinance loan programs, plus grants and second mortgage loans for down payment and/or closing cost assistance.
Purchase and refinance programs
The loan officer’s first task is sorting out whether you are buying or refinancing, and which CHFA program structure fits your income, credit profile, and goals.
One useful detail from CHFA’s materials: the homebuyer education requirement applies to purchase loans, not to refinance programs. A loan officer will flag distinctions like that early so you do not do unnecessary work.
Down payment and closing cost assistance
Down payment assistance through CHFA comes in two forms: grants and second mortgage loans. Each interacts differently with the first mortgage, and the loan officer explains how each option would sit alongside the primary loan.
For buyers in Colorado Springs juggling closing costs, a down payment, and moving expenses — sometimes on a PCS timeline — this is often the conversation that decides whether a purchase is workable now or later.
Once a program direction is set, the loan officer turns to CHFA’s baseline requirements.
Reviewing CHFA’s general program requirements with you
CHFA publishes general requirements for its purchase loans, and the Participating Lender you choose is the party that verifies them. Here is what the loan officer checks.
Credit score
CHFA requires borrowers to have a mid-credit score at or above the minimum the agency publishes. The loan officer pulls a credit report, identifies the mid score, and tells you where you stand against the current threshold.
Income limits
Borrower income must not exceed CHFA’s income limits. The loan officer calculates your qualifying income the way the program counts it and confirms it against the current limit for the program you are pursuing.
Homebuyer education
Every borrower must individually and independently complete a CHFA-approved homebuyer education class before the mortgage loan closing date. The loan officer makes sure this box is checked in time — more on the class below.
Minimum borrower financial contribution
CHFA requires a minimum borrower financial contribution toward the purchase of the home, set at a fixed amount the loan officer will confirm with you. The loan officer documents that contribution in the file.
Lender underwriting on top of CHFA rules
Meeting CHFA’s program requirements is not the finish line. Borrowers must also qualify under the underwriting guidelines of the CHFA Participating Lender, which is where documentation of income, assets, and the rest of a standard mortgage file comes in.
One requirement deserves its own section, because it trips up more timelines than any other: the homebuyer education class.
Helping you complete the homebuyer education requirement
All CHFA borrowers must individually register for and complete a CHFA-approved homebuyer education class before closing. Each borrower on the loan must obtain their own certificate of completion.
In-person and online formats
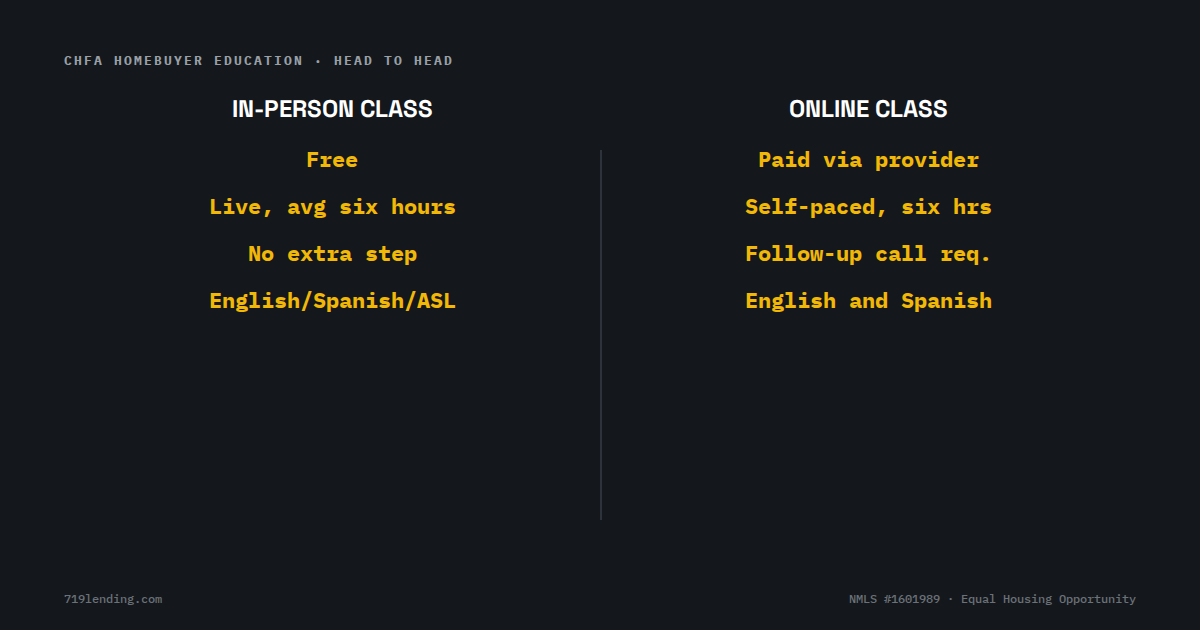
Classes are available across Colorado through CHFA-approved homebuyer education providers. In-person classes are free and run as a live course; online classes are self-paced, carry a fee, and require a follow-up call with the education provider before the certificate is issued.
Classes are offered in English and in Spanish, and CHFA directs borrowers to contact the education provider if language translation or ASL services are needed.
Why the loan officer pushes you to take it early
Certificates are valid for a limited period, and a borrower must be under contract to purchase a home before the certificate expires. CHFA recommends taking the class early, because waiting may delay or postpone your closing.
The certificate comes from the education provider, not from CHFA. Your loan officer collects it for the loan file — another small handoff the loan officer manages so it does not stall your closing.
The class also covers ground the loan officer will build on, which is worth knowing before you sit down together.
What the class covers — and how the loan officer builds on it
CHFA’s homebuyer education curriculum teaches you how to create a budget as a homeowner, how credit impacts homebuying options and how to improve credit, how to find a real estate agent and a lender, the costs of homebuying and the approval process, and what to expect after closing.
A good loan officer picks up where the class leaves off. The class gives you the framework; the loan officer applies it to your actual credit report, income, and target purchase.
CHFA even recommends taking the class early in your housing search so you are prepared to find a lender and a real estate agent who are the best fit for you.
Which raises the practical question: how do you find that loan officer in the first place?
How do I find a CHFA loan officer?
CHFA maintains a searchable list of loan officers on its Find a Participating Lender page. You may work with any loan officer who appears on that list or who works for a CHFA Participating Lender.
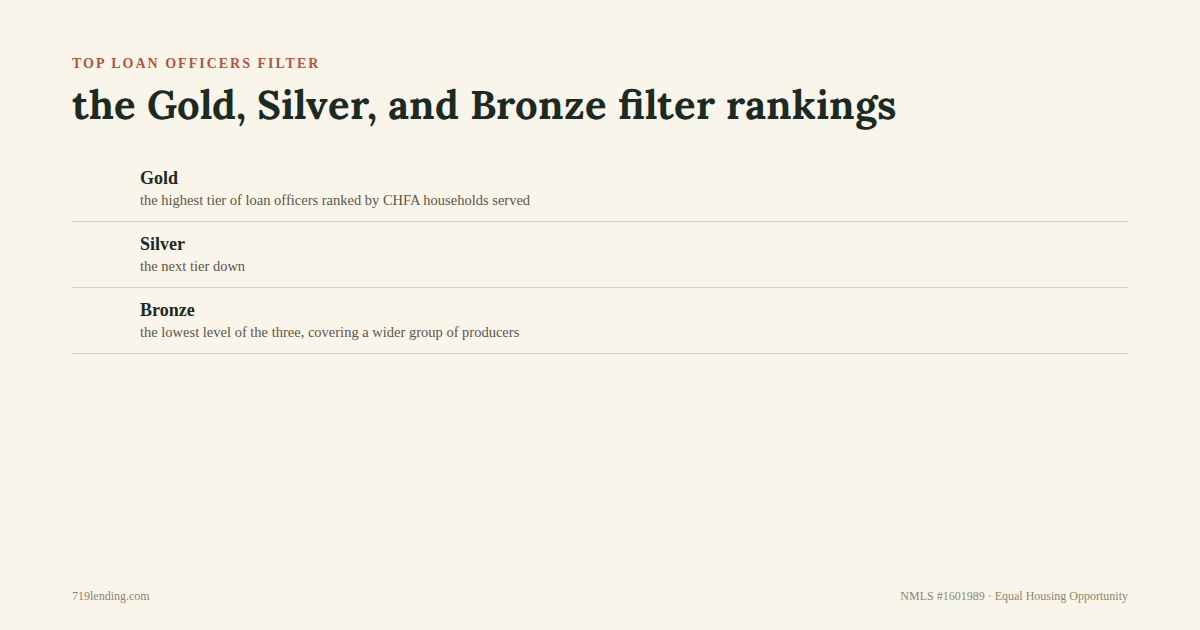
The search offers optional filters. Results are determined by the number of households that used a CHFA loan program while working with that loan officer over the previous calendar year or the most recent rolling twelve-month period.
| Filter | What it shows |
|---|---|
| County | Loan officers who helped a household purchase a home in a specific county in the prior period — useful for narrowing to El Paso County |
| Top Loan Officers | Gold, Silver, and Bronze statuses based on the number of CHFA loans completed in the previous calendar year |
| Households Served | Loan officers in the highest tier of serving households within a certain demographic in the prior period |
| Language | Loan officers who reported to CHFA that they speak languages other than English |
| Lender Advisory Group | Loan officers who serve on CHFA’s Lender Advisory Group, which shares feedback to help guide affordable housing in Colorado |
Two caveats CHFA states directly: filters do not indicate that a loan officer only serves a certain population or county, and the results do not constitute an endorsement or referral by CHFA or a guarantee of quality of service, outcomes, or results.
For military households around Fort Carson, Peterson, and the Academy, the county filter is a practical way to surface loan officers with recent CHFA closings in the Colorado Springs area.
Before you pick anyone, it helps to read what the agency itself publishes.
What the official source says and where to read it
Everything in this article comes from CHFA’s own homeownership pages. The How to Get a CHFA Loan page lays out the general program requirements and the two important next steps: take a homebuyer education class and contact a CHFA Participating Lender.
The Homebuyer Education page covers class formats, certificates, and the steps to complete the requirement without delaying your closing.
CHFA also publishes an interactive Homebuyer’s Roadmap that walks through stops on the homebuying journey, which you can follow in order or jump around based on where you are in the process.
Because CHFA updates income limits, minimum contribution amounts, and score thresholds over time, treat the agency’s site and your loan officer as the source of the current figures rather than any article, including this one.
That leaves one thing: getting started.
Your next step
Start with the homebuyer education class if you are buying — CHFA recommends taking it early, and the certificate has to be in your loan file before closing.
Then talk to a loan officer at a CHFA Participating Lender. Bring your questions about income limits, credit, down payment assistance, and timing; qualifying questions belong with the lender, since CHFA does not qualify homebuyers itself.
719 Lending works with Colorado buyers, including first-time buyers and military families across Colorado Springs, on exactly these conversations. Reach out and we will walk through whether a CHFA program fits your purchase.
Frequently asked questions
Does CHFA lend money directly to homebuyers?
No. CHFA states that it does not lend money directly to consumers. It uses approved Participating Lenders to qualify customers and make all mortgage loans, so every CHFA loan starts with a loan officer at a Participating Lender.
Can I work with any CHFA loan officer?
Yes. A homebuyer may work with any loan officer who works for a CHFA Participating Lender. The filters on CHFA’s lender search — county, language, production status, and others — are a convenience, not a restriction or an endorsement by CHFA.
Do I have to take a class to get a CHFA loan?
For purchase loans, yes. Each borrower must individually complete a CHFA-approved homebuyer education class before the closing date and provide their own certificate of completion to the lender. The requirement does not apply to CHFA refinance programs.
What are CHFA’s general requirements for a purchase loan?
Borrowers need a mid-credit score at or above CHFA’s published minimum, income within CHFA’s income limits, a completed CHFA-approved homebuyer education class before closing, and a minimum borrower financial contribution toward the purchase. Borrowers must also qualify under the Participating Lender’s own underwriting guidelines.
Does CHFA help with down payment or closing costs?
Through its Participating Lenders, CHFA offers grants and second mortgage loans for down payment and/or closing cost assistance. A CHFA loan officer explains how each option works alongside the first mortgage and which ones you may be eligible for.
What do the Gold, Silver, and Bronze labels mean on CHFA’s lender list?
They are production statuses based on the number of CHFA loans a loan officer completed in the previous calendar year. CHFA notes the results reflect households served and do not constitute an endorsement or a guarantee of service quality or outcomes.
719 Lending Inc., NMLS #1601989 · Equal Housing Opportunity
719 Lending Inc. is not affiliated with or endorsed by HUD, FHA, VA, USDA, CHFA, the CFPB, or any government agency.
Last updated: September 2026

Related Posts